


Research Note: Evolve’s Recap of ITC Vegas and National Comp 2026
What Evolve saw at ITC Vegas and National Comp in Las Vegas, September 29 to October 1, 2026
Five ITCs, one direction. Before this year’s recap, here is how the floor has moved year over year, drawn from Evolve’s own ITC write-ups.
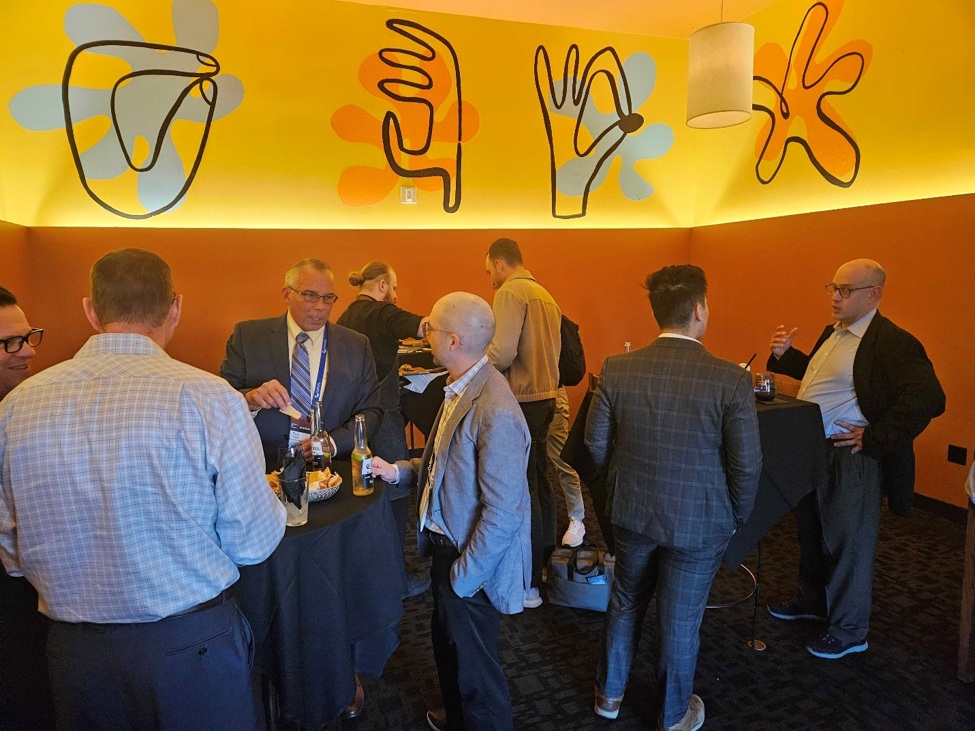
At this year’s InsureTech Connect in Las Vegas, held September 29 to October 1 at Mandalay Bay (where Evolve hosted our private, invite-only Merge & Mingle mixer at Border Grill on the evening of day two, with photos below), we spent three days in back-to-back meetings with carriers, MGAs, software and services providers, strategic acquirers, and capital partners. National Comp, the national workers’ compensation conference, ran in the same building on September 29 and 30, and our team split time between the two locations.
ITC Vegas 2026: Everything AI, Nothing AI
In June, we left ITI New York writing that there was more AI than ever and that it had barely moved the numbers that matter. Three months later, the booths were bigger (one vendor put up a screen two stories tall), the AI language was louder, and buyers were noticeably harder to impress. The line we heard repeated most often came from an investor at his first ITC, after a full day walking the floor with his operating partner:
“Everything AI, but nothing is AI.”
What he meant was a floor full of tools that each automate one small task, and very few that change how an agency or a carrier actually runs. Most of the conversations below came back to that gap, and to how buyers are responding to it.
Key Themes Evolve Observed
1) AI is the default pitch, so buyers are grading on proof
Takeaway: The AI label costs nothing now. What earned a second meeting was a specific workflow, named customers, and accuracy that holds up inside an insurance process.
- Capital is still chasing the label. AI-focused companies took 99.1% of the $2.44 billion invested in insurtech globally in Q2 2026, and every round above $5 million went to an AI-focused business. On the floor, a lot of that money showed up as narrow point tools. One investor building an agency platform told us he spent the day looking for anything that would help an agency sell more to new customers and came away empty-handed.
- One strategic acquirer sat through more than two dozen AI vendor meetings during the week. Its approach is to partner first, with a revenue share, and to buy only once a product covers a full workflow across lines rather than a single step.
- Accuracy is the real filter. The CEO of an acquisitive underwriting technology company told us at our mixer that in underwriting, being right 80% of the time is not good enough. It has to be closer to 98%, and it has to give the same answer twice. A colleague of his described today’s best AI as a very good intern: excellent with specific instructions, but not a replacement for someone with 25 years in the seat.
2) Integration and data decide the deal
Takeaway: Buyers cared less about the demo than about how easily a product fits into the systems and data their clients already run.
- The questions were practical. Who are the clients, how deep do those relationships go, and does the product work with the agency management and CRM systems those clients already use? One buyer told us a tool built around a single CRM counts against it.
- Founders described the same problem from the other side. A policy administration team building an AI analyst for carrier executives said the product was the easier part. The hard part is getting a client’s data loaded without their own people in the loop.
- A speaker series panel on modernizing life and annuity policy administration made the same point from the carrier side. The panelists agreed that project estimates rarely miss because of the technology. They miss because of how quickly decisions get made, how often they get reopened, and how tangled the surrounding systems are, such as 30-year-old commission platforms with complex hierarchies. One speaker compared running the legacy and new systems side by side to renting two apartments at once. Their advice was to remodel one room at a time: ship a minimum viable product and iterate. One carrier on the panel turns around user-requested changes to its new workflow tool in 2 to 3 days.
- The money has to keep up with the front end. The official banking sponsor at ITC told us the same problem came up from every seat in the distribution chain: agencies chasing premium and reconciling trust accounts, MGAs adding accounts and remittances with every new program, MGUs and fronting carriers needing to see that premium is moving and kept separate at each step. A premium dollar passes through 3 to 4 parties before it lands, and each handoff is a delay and a reconciliation. AI is speeding up quoting and binding. The plumbing behind it has not caught up.
3) Strategics are buying, on their own terms
Takeaway: Acquirers would rather buy than build, but they are holding firm on price and will walk away when the numbers do not work.
- Pipelines are active. An underwriting technology buyer told us it would sooner acquire an agency distribution channel than build one. A large insurer looking to grow in commercial lines has set its floor at $250 million, on the view that integrating a $50 million company takes as much effort as integrating a $500 million one.
- That discipline is showing up in live deals. One acquisitive claims firm has walked away twice late in diligence, and on another target its valuation came in at less than half of the seller’s ask.
- Early-stage capital is getting scarcer. Early-stage insurtech funding fell 51.8% from Q1 to Q2 2026, even as total funding reached a four-year high. A buyer at our mixer expects that to feed M&A: plenty of companies sitting between Series A and Series B will not reach the growth rates venture investors want, and they will need another path. “That’s where we come in,” he said.
- Workers’ comp is drawing specialty buyers. In our July 2026 M&A update we noted ANV’s acquisition of Specialty Comp Insurance Solutions, roughly $250 million of specialty workers’ comp premium, and Sompo’s agreement to acquire Service Insurance Companies, both targeting underserved, hard-to-place niches. That is the same buyer logic we heard on the National Comp floor.
- Claims services roll-ups are not new, they are just quieter. The sponsor-backed investigations platform we met this year is following a pattern that runs straight back to the Gallagher Bassett and Davies add-ons we covered in 2022: private equity-backed adjusting, investigation, and subrogation platforms buying capabilities one at a time and using access to top-10 carriers as the rationale. Evolve has tracked that buyer set continuously for four years.
4) Everyone is selling to MGAs, and capacity still sets the pace
Takeaway: Designing an MGA product costs less than most founders think. Lining up capacity and seed capital is still the slow part.
- “Everyone wants to sell everything to MGAs,” one investor told us after walking the expo, and the floor backed him up.
- On the build side, an actuarial practice that designs MGA products told us a typical product costs $200,000 to $400,000, not the $2 million founders often hear, and a simple student cyber product came in around $50,000. What holds launches back is finding broker and capacity partners and raising seed money. One early-stage MGA we met is raising a round that hinges on first locking in reinsurance.
- Parametric flood and wildfire products came up in several conversations. Regulators are more open to them as traditional capacity pulls back, and the bigger hurdle now is educating brokers.
5) The same AI that speeds up claims is making fraud easier
Takeaway: Straight-through claims and AI-generated evidence are on a collision course. Detection has to be built into the automation, with a person making the final call.
- At ITC’s “Fight Fire with Fire” speaker series session, a panelist who has spent about 20 years in insurance fraud detection said one UK insurer reported a 300% jump in AI-generated claim images in a single year, and that 99% of carriers in a recent survey had seen manipulated images in claims. Watermarking tools are easy to get around. His view: carriers that build manipulation detection into their claims automation can stay 1 or 2 steps behind fraudsters, while those that do not are 20 steps behind.
- The catch is customer experience. If every flag goes to a reviewer, false positives slow down good customers, so a flagged file needs to be something an adjuster or investigator can decide on in under a minute. Another panelist said the carriers furthest along treat governance as a competitive advantage, and roughly 60% of that group is seeing a 2-to-1 return on its AI spend.
Down the Hall at National Comp
National Comp ran alongside ITC in the same building, and walking between the two was one of the more useful parts of the week. The ITC floor was mostly technology looking for a workflow. National Comp was mostly cost, care decisions, and accountability, and the businesses there were built around expert judgment.
- Independent review firms that handle pre-authorizations and appeals under state treatment guidelines were clear that those decisions stay with qualified clinicians.
- A private equity partner we first met at ITI New York in June has met roughly 15 companies in med-legal services. His view was simple: AI can help approve a straightforward claim, but denying one, or weighing in on treatment, still needs a doctor. The harder question for a roll-up is which pieces belong together, since an early-stage workers’ comp review business and a late-stage personal injury expert practice do not naturally fit.
- A public-entity risk management team won a Theo Award, one of about 20 given nationally each year, for charging each department its own share of injury costs. Workers’ comp injuries came down even as headcount grew, without any new software.
- Workers’ comp TPAs hold value through benefit expansions. Our own transaction work this past year made the case that a TPA’s ability to manage rising medical costs and complex indemnity exposures is what keeps its valuation resilient as states expand benefits (Minnesota’s PTSD expansion and California’s indexed benefits, both 2024, and NCCI filings showing improving loss trends). The businesses at National Comp are built on exactly that judgment, which is why the buyers who understand it keep showing up.
Who We Met, and Why It Was Interesting
Highlights below are generalized and anonymized:
- A vertical AI company serving brokers.
Growing 2 to 3 times a year on an outbound sales model rather than marketing spend. The founder told us conferences produce fewer leads than people assume, and that his time at ITC goes to meetings with the largest brokers. - A founder-owned insurance software services firm.
Nearly all of its work comes by referral, and demand is ahead of what the team can take on. Not for sale, though the owner would hear a substantial strategic offer from a buyer that would look after his people. - A sponsor-backed insurance investigations platform.
Built through a long run of acquisitions and now moving into adjacent claims services such as subrogation, forensic engineering, medical records retrieval, and IMEs. A disciplined roll-up in a corner of the market that rarely gets a big booth. - An agency AI startup founded by agency owners.
Built by a family whose agency dates back more than a century, and now piloting with a large agency network. It is raising a seed round, which is early for us, and it is a company we plan to revisit at Series A.
The Evolve Team Takeaways
- Seed stage, again.
Several founders we met were raising a seed round now or planning one next quarter, with Series A still a year or more away. - The best-run owners are buyers.
Some of the strongest businesses we met are not for sale. They are acquiring, and a few would still take a call on a substantial strategic offer. - New names in the buyer pool.
A global insurance distribution group told us it is looking at Canadian distribution businesses, and we met offshore technology services firms that could become natural buyers of insurance IT services companies. - The best meetings happened off the floor.
A private equity partner on his 8th or 9th ITC told us nearly all of his meetings now happen outside the expo hall. A buyer added that ITC is excellent for partnership meetings, since every vendor is in one place, and less useful for reaching decision makers. - Relationships compound.
At our mixer, a technology vendor one of us first met 1 to 2 years ago stopped by to tell us its East Coast insurer client had finally gone into production. A group that first met our team at ITI came to find us again, and several people we had only known by email introduced themselves in person. None of that shows up in the conference app, and it is a big part of why we keep coming back.
Five Years of ITC, One Direction
We have written up ITC since 2023 and kept notes since 2022. Read side by side, the story is not that 2026 was the year buyers got skeptical. It is that they have been getting more discriminating every single year, and this year the AI label finally stopped covering for it.
Five through-lines we would stand behind:
- Discipline compounds.
The buyer has gotten more discriminating every year since 2022. The 2023 washout of napkin companies, the 2025 shift from wrappers to workflow, and this year’s proof bar are one continuous line, not a 2026 surprise. - Capital rotated, it did not disappear.
From “more PE interest” in 2022 to “tighter funding” in 2023 to a barbell in 2025 to AI taking 99% of the dollars in 2026. The seed-stage overhang we describe below is the predictable result. - Claims services never left.
They showed up as efficiency-seekers in 2023, thinned on the 2025 floor, and are back in 2026 as PE roll-ups and across the hall at National Comp. The buyer set has been active the whole time. - Tech augments the expert.
We said it in 2023, the chess-engine analogy made the point in 2025, and this year it is the consensus read, from the dot-com investor at our mixer to the clinicians at National Comp. - MGA capacity is the constant.
Reinsurance capacity was the constraint in 2022 and it is still the constraint in 2026. What changed is that building the product got cheap.
How Our Read Aligns with Public Recaps
ITC framed 2026 around “The Horizon of Possibilities: Predict, Prepare, Progress,” with agentic AI at the center of the agenda. We would not argue with the possibilities. What changed since June is the order of the questions buyers ask. They no longer start with whether a company uses AI. They start with who is already using it, how it plugs in, and how often it is right.
The public read is more mixed than the stage suggested. Attendee ratings we reviewed scored ITC strongest on price-to-value and the density of decision makers, and weakest on curation and speaker caliber, the view being that open access dilutes the executive signal. That matches what the private equity partner on his 9th ITC told us about meeting off the floor. And on LinkedIn, vendors and carriers who were not in the same rooms as us converged on nearly the same sentence: the question is no longer whether insurers should use AI, it is how to make it work.
A private equity investor at our mixer, whose firm lived through the dot-com cycle, put it in perspective. Every business ended up on the internet, but the internet did not replace every business. He expects AI to follow the same path and find its way into everything as a tool. For founders, that means a narrow product may be most valuable as part of someone else’s platform, which makes a well-run sale a strong outcome. For investors, services businesses with an expert in the middle look more durable than the hype suggests.
Closing
If you would like to compare notes on what we are seeing in technology-enabled insurance services and software, we would be glad to connect. Thank you to everyone who joined us at Border Grill. Evolve is a growing presence in insurance M&A, and whether you’re a founder or investor considering a transaction now or planning for the future, we would welcome the conversation.